The most common question we get at Axal is:
How do you get 7.6% APY?
Axal gets 6-10% APY by lending your cash to folks who want to borrow it.
That’s literally it.
Lending has existed for thousands of years all over the world. The difference here is you have the ability to lend directly to borrowers, 24/7, with no intermediaries pocketing fees.
Banks take your money and lend it out. They pocket the interest for themselves, paying you pennies (literally). Oftentimes, their loans are undercollateralized (meaning borrowers could default and banks eat that loss). What if you could lend direct?
The APY is generated from overcollateralized stablecoin lending markets. Stablecoins are just digital dollars (Axal uses USDC from Circle, a publicly traded and federally regulated company in the US). Blockchains allow us to help users lend direct - code tracks loan repayments, liquidates borrowers, and because loans are overcollateralized, you know your principal is designed to be protected.
Here’s an example. If you put $1000 into Axal, we diversify those funds across several of these lending markets. Say one of the markets has a borrower who is borrowing $100 of your dollars. In order to do this, they put up in escrow $140 of Bitcoin (they are borrowing against this collateral). If they fail to maintain an overcollateralization ratio of say 120% (if Bitcoin goes down) or miss loan repayments, that collateral is liquidated, cashed out, and returned to you. As a result, your principal is safe.
Rules aren’t governed by subjective judgements at a bank window or over a call - immutable code ensures rules can’t switch up on you (not the case for banks or conventional loans). What you see is what you get.
What’s the catch?
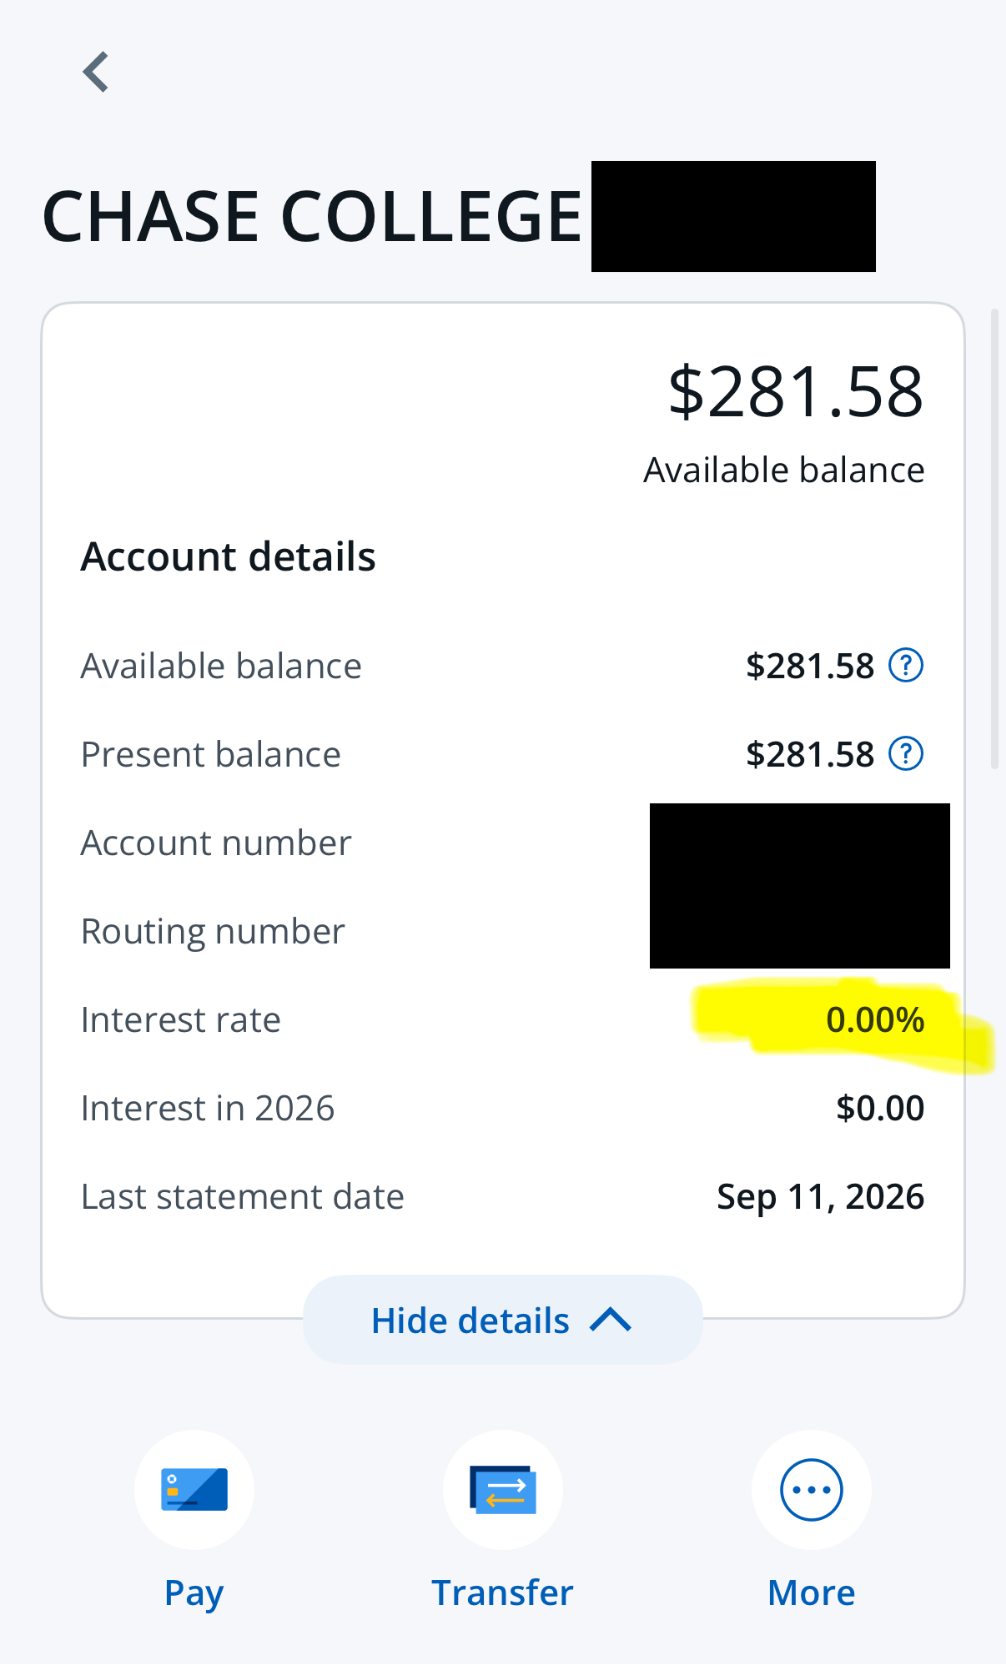
I get it - a number this high when folks are used to 0% on their cash is shocking. My own Chase College account publicly announces that I’m earning nothing (thanks for rubbing it in Chase).
As with any place giving you a return of over 0%, there is no free lunch. Our job at Axal is to ensure people aren’t taking excessive risk for the returns they are receiving, but at the same time aren’t doing nothing with their money. We believe that stablecoin yield is an exciting solution that most folks should allocate to!
Don’t gamble your wealth, and don’t do nothing. Pretty simple principles.
Here’s what to keep in mind:
- Rates are dynamic. Just like any market, supply and demand can impact the rates you see. Axal’s rebalancer automatically re-allocates your funds according to rates, liquidity, and other risk factors (with scoped permissions on what it can/cannot do). This helps mitigate downside while maximizing upside if we see rate spikes on one market over others without additional risk!
- The generally higher rate than conventional savings products stems from 2 forces: a premium for permissionless lending, and smart contract/technical risk being priced in. It makes sense that a system where anyone can borrow or lend, 24/7, anywhere on Earth, against assets that were previously idle, commands a premium. At the same time, as with any new financial product, there is a “battle tested” feeling that a century old institution has that has not been rivaled (yet). A bug in code for liquidating borrowers who don’t repay/post more collateral could risk the lender principal.
- Axal is a financial technology company, not a bank with FDIC. FDIC insures against bank defaults up to $250K. With Axal, “defaults” or runs in a traditional sense aren’t possible, since you always have 24/7 access to your funds (self-custodial, no one, not even Axal, can restrict this). However, this is a key difference from conventional savings products.
Our job at Axal is to mitigate risks as best we can. Here are some of our values:
- Only allocate to bluechip markets with significant liquidity for instant withdrawals.
- Diversify across multiple markets to mitigate downside risk.
- Ensure collateral is proven (not as volatile), conservative LTV ratios so liquidations can happen with room to spare during crashes, and a rebalancer that is constantly monitoring everything (rates, demand/supply shocks, etc.).
- Lend dollars only (no other asset risk). Axal specifically only uses USDC, the definitive American stablecoin regulated federally by the GENIUS Act and issued by Circle, a publicly traded company. Other yield products have historically promised “dollar yield” without actually having proven dollars under the hood, putting users at risk. We’ve intentionally stuck to dollars that are interoperable with cash in your bank.
- Allocate to proven markets. Top institutions like BlackRock, Apollo and Fidelity, and major fintechs like Robinhood and Coinbase, have researched and allocated to the same class of markets that Axal does.
- Self-custodial by design. There is no Axal “going down locks your money” risk in the custodial-bank sense, because users always control the private key to their funds. This means you can move funds whenever you want to different platforms (no matter what).
- No lockups or minimums. Deposit or withdraw $1 or $1,000,000 dollars to and from external bank accounts. No matter what. No need to get permission from anyone (not even Axal).
Why haven’t I heard of this before?
There are a ton of things to perfect before direct lending can go mainstream! At Axal, we believe the time is finally right for consumers to tap into these markets.
The underlying infrastructure of these markets has taken over a decade to get right. Getting significant capital moving through these markets took time, only recently hitting amounts that serious institutions are comfortable with (hundreds of billions in stablecoins). Proving that the code behind the markets can be battletested has taken time. Getting U.S. regulation at a federal level took time.
The final step? Making all this accessible. Abstracting away transaction processing, rebalancing, and creating a magical, buttery user experience. That’s our mission at Axal!
How do I start earning?
It’s easy! Download the Axal app (App Store, Google Play), sign up with email, and deposit. It takes ~2 minutes to verify your identity and initiate a bank deposit, or you can instantly deposit via Apple Pay, from existing fintech apps like Robinhood and Coinbase, or send stablecoins!
Building trust with your money takes time. The easiest way to understand how Axal could fit into your financial life is by trying it out and seeing it with your own eyes.
If you have any questions or want to learn more, feel free to reach out to me directly at ash@axal.com or 781-971-9463. And stay tuned for more announcements and features on our road to self-driving wealth.